Monday, January 11, 2016

Amid Stock Market Panic, Dozens of Chinese Billionaires Are Mysteriously Disappearing

By John Vibes
Amid stock market panic in China, many of the country’s most prominent billionaires are disappearing without a trace. This week, Zhou Chengjian, the chairman of the clothing company Metersbonwe became the most recent wealthy Chinese businessperson to go missing. Metersbonwe said in a statement on Thursday that it would be suspending its shares on the Shenzhen Stock Exchange and that they were unaware of Chengjian’s whereabouts.
According to Bloomberg, as many as 36 companies reported executives missing from January to September.

Just a few weeks ago, Chang Xiaobing, the CEO of the state-owned telecoms giant China Telecom, resigned and then went missing. There were rumors that Xiaobing was taken by police or government agents in a widening corruption investigation that is touching every corner of the Chinese economy.
Back in November, Yim Fung, chairman and CEO of Guotai Junan International Holdings went missing, sending the company’s stock down 12%. Also in November, Chen Jun and Yan Jianlin, two senior executives of Citic Securities vanished without a trace.
In October, Zhang Yun, the president of the Agricultural Bank of China, also disappeared, however, it was reported that he was detained as a part of a corruption investigation.
Earlier this year, in June, Poon Ho Man, the CEO of China Aircraft Leasing Group went on vacation and never came back. He resigned while he was gone and has not been contacted since. Xu Jun, chairman of the department-store operator Ningbo Zhongbai is another Chinese executive who disappeared this year. It was confirmed by Xinhua news agency was being investigated for corruption at the time of his disappearance.
Dozens of other wealthy executives throughout China have disappeared in the past year, many of them under different circumstances. It is apparent that there is a growing corruption investigation in which many of these executives are implicated. However, only a small number of them have been officially announced as being in government custody. With that being the case, it is likely that some of the executives have fled and are in hiding expecting that they will soon be jailed. It is also possible that the government is sweeping them up in the middle of the night, as secret police in dictatorships have been known to do throughout history.
Also, it is unclear whether these corruption investigations are witch hunts, designed to place blame for the declining economy, or if it is a legitimate effort to keep bankers and executives accountable for their actions. There is no doubt that the government was involved in whatever corruption may have been taking place, but as always they are in charge of the investigation so it is unlikely that any government agents or employees will be implicated.
John Vibes is an author and researcher who organizes a number of large events including the Free Your Mind Conference. He also has a publishing company where he offers a censorship free platform for both fiction and non-fiction writers. You can contact him and stay connected to his work at his Facebook page. You can purchase his books, or get your own book published at his website www.JohnVibes.com.

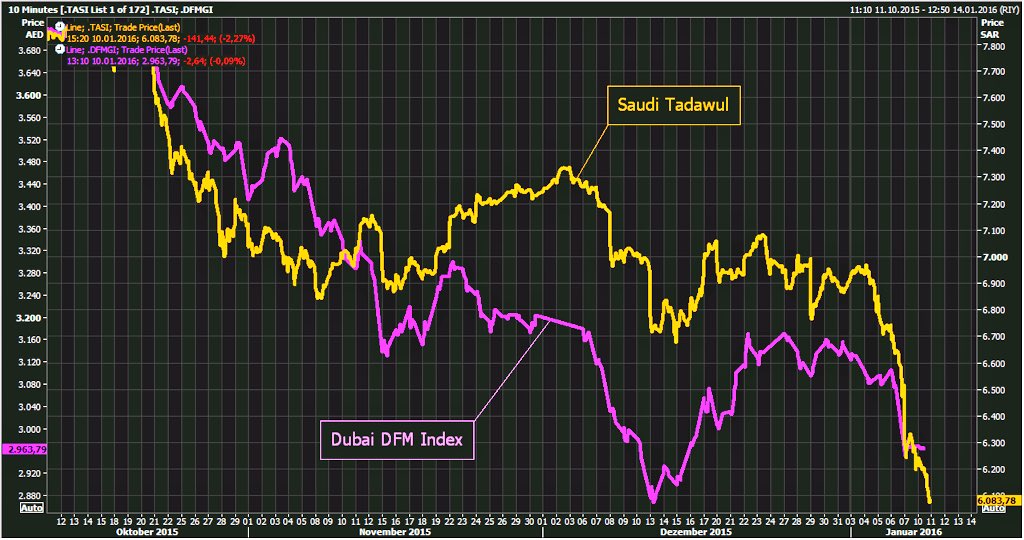
Middle East stocks continue to drop w/ Saudi’s Tadawul down >2% as investors spooked by China doom & depressed oil.

Middle East stocks continue to drop w/ Saudi's Tadawul down >2% as investors spooked by doom & depressed oil.

Goldman Sachs: Higher Ed Ripe for Disruption

A Goldman Sachs investment research report issued last month paints a very grim picture of the state of American higher education (h/t Bryan Alexander). The bottom line: “returns on a college education are falling,” and quickly.
According to a striking graph included in the report, the average “wage premium” from going to a four-year college (that is, the difference in incomes between college graduates and high school graduates) and college tuition (including room and board) rose in tandem throughout the 1990s. Then, starting in about 2002, something changed—the wage premium growth started growing more slowly, even as tuition kept rising as fast as ever.This disconnect, Goldman notes, is not a problem for all classes of colleges. It appears that the top institutions (as ranked by SAT scores) are still delivering good returns, while the returns for schools in the bottom half, and especially the bottom quarter, are falling off steeply. This can’t go on forever. If costs continue to exceed returns, the bubble will burst eventually—even if Washington keeps subsidizing it.Finally, Goldman summarizes possible avenues for a shakeup of the higher education system:
Two things in particular stand out as potentially disruptive to universities. First if employers changed their attitude toward nontraditional sources of degree awards. Massive open online courses (MOOCs) are the most obvious threat (30% of undergraduates already take some classes on line), but it could also be companies creating their own de facto degrees. Udacity for example offers nanodegree programs where curricula are designed in partnership with companies like Google, AT&T, Facebook, Salesforce and Cloudera. Second, for a broader new system of signaling and talent identification, look again to the tech sector; an increasing numbers of companies are using GitHub (a software development tool used for writing, storing and collaborating on code) to view coders’ portfolios of work as a better talent indicator than their academic resume. Consulting firms EY and PWC have both said they will use their own testing systems for recruitment rather than relying on academic grades.
Both of these avenues should be pursued aggressively. We’ve written before that despite the protestations of academic insiders, MOOCs have real promise—not just as supplements to brick-and-mortar degree programs, but as viable alternatives for large numbers of students. And a “new system of signaling and talent identification” is sorely needed. A national exam system, in particular, would help level the playing field for students who didn’t want to attend an elite college, or couldn’t afford to.
The current American higher education regime is not working for a huge number of students, and, as this report suggests, those who continue to cling to the status quo are in denial. The system has to change, and it will.

This is What Happens after PE Firms Get Through with a Retailer

Wolf Richter wolfstreet.com, www.amazon.com/author/wolfrichter

At least, they didn’t blame China.

Thursday afterhours, the Container Store, former LBO queen and IPO hero with 77 stores around the country, reported third quarter “earnings” – in quotes because those “earnings” were a loss.
Consolidated net sales for the quarter ending November 30 rose 3.3% to $197.2 million. But cost of sales rose 5.3%. CEO Kip Tindell blamed their new “$75 free-shipping service.” It’s “driving sales” and is “absolutely a good thing, but of course it’s a headwind to gross margin,” he said. That’s how Amazon leaves its mark.
Selling, general, and administrative expenses jumped 8.6%. “Disappointing,” Tindell called it. CFO Jodi Taylor blamed the “complexity of our transformational TCS Closets initiative,” plus higher payroll, healthcare, and storage expenses. Stuff happens in real life.
Stock-based compensation, pre-opening costs, and depreciation and amortization also rose. So income from operations plunged 87% to $1.8 million. And after $4.2 million in interest expense and a tax benefit of $694,000, there was a net loss of $1.7 million. It brought the net loss for the nine months to $4.3 million.
The company had lost money in fiscal 2013 and 2014 and had made a little in fiscal 2015. All hopes are resting on fiscal 2016 as the big profit year. But the company had some more news:
It cut its sales projections for fiscal 2016 at the midpoint by about 2% to $785-$795 million. It slashed its earnings projections from 30-38 cents a share to 10-13 cents. It projected that sales at established stores – stores open at least 16 months, plus online sales – would fall 1% to 1.6% for the year, and 3% to 5% for the fourth quarter.
All heck broke loose. Before the announcement, shares had closed at a new low of $7.06. In afterhours trading, they got pummeled. And on today, shares crashed 41% to close at $4.21.
As so many debacles, this one too has a private equity angle.
The Container Store, founded in 1978, was acquired by PE firm Leonard Green in July 2007, at the peak of the LBO frenzy. In November 2013, the “IPO window” – that brief period when anything can be sold at ludicrous prices and then get pumped up even higher as exuberance and hype rule – was wide open. And it was time to unload. The IPO price was set at $18 per share. Overnight, Wall Street machinations doubled the price behind closed doors. The first trade took place at $36 per share. The company became the hero of Wall Street.
So forget the losses it had been cranking out.
The stock then soared to $47.07 in two months. But early 2014, the hot air began hissing out. Today it’s down 88% from when it first started trading and down 91% from its peak two months after its IPO. This is how IPOs function as wealth-transfer machines.
Tindell tried to do the best he could. During the earnings call (via Seeking Alpha), he talked about “a choppy retail environment and softer than planned November,” his euphemism for the Thanksgiving shopping debacle.
And the rest of the shopping season? “The start to the fourth quarter has also been more challenging, which we have reflected in our revised outlook,” he said – his euphemism for the Christmas shopping debacle.
After going through how they’ve been spending more than planned, and how “disappointing” those expenses were, Tindell then pointed to the future, not the immediate quarter whose projections he’d slashed, but the more distant future, when the “greatest impact” of their efforts would be felt,  namely “in 2016 and beyond.” In brick-and-mortar retail these days, the good times are always in the distant future.
The Container Store isn’t the only one. Other brick-and-mortar retailers are struggling, particularly those that have been bought out by PE firms that piled debt on these companies and paid themselves fat fees and special dividends. Now these retailers have trouble borrowing more money at reasonable costs. They’re junk-rated, and at the lower end of the spectrum, credit is drying up. Risks that everyone refused to see are suddenly getting priced in. They’re suffocating on interest costs. Some already ran out of liquidity last year and defaulted, and more will in 2016.
They’re facing a very tough retail environment. American consumers are strung-out. But for brick-and-mortar retailers, the problems are worse: sales have been shifting to the internet. And then there are the Millennials, the Holy Grail for retailers.
Millennials make up the largest age demographic, and their earnings power is increasing. But they’re smart and have ideas of their own and refuse to be roped in massively with the usual tricks and devices. Instead they’re inexplicably frugal when it comes to things like clothes. But they love to blow their money on experiences, such as restaurants and going places, and on their electronic lives, their smartphones, gadgets, broadband bills, and Netflix accounts. And they do much of their shopping online.
More and more brick-and-mortar retailers are now admitting that they haven’t figured out how to get the attention of these folks.
That’s the reality brick-and-mortar retailers face. PE firm Leonard Green was able to exit from the Container Store in time – a disaster for those who wittingly or unwittingly (in their retirement nest eggs) ended up with these misbegotten shares.
But many of the retailers are still owned by PE firms, such as Neiman Marcus, Albertsons, J. Crew Group, 99 Cents Only Stores, Bon-Ton Stores, Claire Stores, and a slew of others. Exits were planned and IPOs were lined up, but the stock market got the jitters, and the IPO window closed on them. For these over-indebted, junk-rated brick-and-mortar retailers, it’s going to get much tougher. Read…  Defaults and Restructuring Next for Retailers
UK Banking Industry – Most Unstable in G7 Implements Depositor Bail-in Scheme

UK_economyBy Graham Vanbergen
Back in September we published an article “Grand Theft Auto – UK and EU Bank Depositor Bail-In Regime Implemented” in which we described how banks throughout the EU would simply steal your deposits if any of them failed.
The first paragraph stated “Shares and stocks are tumbling around the world, with investors worried that the next global crisis has already begun. There is considerable uncertainty and nervousness amongst economists and trend forecasters. Government’s sooth jittery markets with misinformation in the hope that confidence does not evaporate and their legitimacy with it.”
On the first day of 2016 all banks located within the EU follow the ‘Anglosphere’ nations of Britain, America, Australia, New Zealand and Canada into an agreement, where the next bank failure and bail-in could cost depositors all their money.

Think it won’t happen. Six years after the last financial calamity caused by reckless bankers aided by negligent politicians in late 2014, one in five European banks failed basic stress tests that would see bankruptcy on the first hint of trouble. What did they need to get past that stress test? Twenty four thousand million euros.
One should not forget that the Bank of Cyprus passed its stress test with flying colours just before it crashed and burned. That bail-out and bail-in came in at €23 billion to the taxpayer but it also took 47.5% of depositors money over €100k as well.
Think it won’t happen to British Banks? This from the Financial Times:
The Bank of England’s stress tests of the banking sector have been attacked as “fatally flawed” for setting hurdles that are too easy to clear and giving false comfort about the safety of the financial system.
A report published by the Adam Smith Institute, a free market think-tank, calls for the BoE annual stress tests to be scrapped, arguing they are “worse than useless” because they disguise weakness in the UK banking system.
The BoE has said that banks will be required to meet a minimum 3 per cent leverage ratio to pass 2015 tests. If it had done so in 2014’s tests, half the banks would have failed: Lloyds Banking Group, Royal Bank of Scotland, the Co-op Bank and Santander UK.
An article in right-wing The Telegraph, opined – “Punishing the banking industry punishes the UK as a whole” where it postulates that in 2014 the banking industry contributed over £30bn to the treasury. What this article fails to say is that half of that tax paid was employee taxation, and only £1.6bn paid as corporation tax …. for the entire industry. Don’t forget that banks are still paying billions in fines, used to offset even more tax contributions.
Five of the biggest banking corporations in the world paid no tax on its UK operations, whilst many others paid very little, their contribution to an austerity ridden nation caused by their malicious and egregious abuses being next to nothing.
Labour MP, John Mann, said:
The tax receipts from these large financial institutions show what a charade their claim to pay their fair share has become. They rely on the taxpayer to underwrite their risk, yet they pay a minimal return back to the exchequer.
Since our article barely four months ago, the outlook for banking has got a lot worse and more risky.
Banks have returned to the same markets that caused the crash; interest-only mortgages, zero-percent credit cards and what they now term “credit impaired products” or sub-prime to you and me. Consumer credit reached pre-crisis levels last summer and shows no sign of abating. Mortgage providers are engaged in a ‘rate-war’ with nearly 200 providers requiring just 5% deposits.
In 2008, derivatives exposure bankrupted Lehman Brothers  in a $600 billion bankruptcy case that clocked in as the largest bankruptcy filing since the beginning of time.
What was it that toppled the almighty Lehman Brothers – the effects of contagion.

What The Charts Say: "US Stocks Are In Riskiest Position In Seven Years"

Via John Murphy,
MAJOR STOCK INDEXES ENTER CORRECTION TERRITORY... After suffering the worst start to a new year in history, the U.S. stock market has entered correction territory which is defined by a drop of 10% from its old high. The charts pretty much speak for themselves. All three major stock indexes fell to three month lows in heavy trading. The next downside target is the two lows formed in August and late September.

What the indexes do from there will determine whether the current downturn is just a correction or something more serious. Unfortunately, some portions of the market have already broken those support levels.
SMALL AND MIDCAPS BREAK SUPPORT... Relative weakness in small and midsize stocks gave early warnings in December that the yearend rally was mainly a large cap affair and too narrow to continue. That situation has gotten a lot worse since then. Charts 4 and 5 show the Russell 2000 Small Cap and the S&P 400 Mid Cap indexes falling below their 2015 lows. That puts them at the lowest level since October 2014.
 

That's another important test for them and the rest of the market. 
TRANSPORTS ENTER BEAR MARKET TERRITORY... Chart 6 shows the Dow Jones Transportation Average falling to the lowest level in two years. It has lost -25% from its late 2014 high which puts it into bear market territory. What's surprising is that the transports haven't gotten any help from plunging energy prices. That may carry bad news for Dow Theorists who link the direction of the transports with the Dow Industrials.

It may carry good news for the Dow Utilities, however, which are showing more resilience. Chart 7 shows the Dow Utilities holding up a lot better than everything else.

It was the only market sector to register a gain during the week. Its relative strength line (top of chart) is rising as well. Since utilities are considered bond proxies, their relative strength large reflects the recent rotation out of stocks and into bonds.
BOND/STOCK RATIO FAVORS BONDS... As usually happens when stocks fall, bond prices are rising. That's especially true of longer-dated Treasury bonds. The green line in Chart 8 is a ratio of the 7-10 Year Treasury Bond ishares divided by the S&P 500 SPDRs. The ratio spiked last August when stocks tumbled.

The ratio has spiked again to the highest level in three months. Bond prices are also benefitting from the deflationary impact from falling commodity prices. Two other assets attracting safe haven buying are gold and the Japanese yen. Some measures of foreign stocks (both developed and emerging) have already fallen to 52-week lows. That doesn't bode well for U.S. stocks which are now in the riskiest position since the bull market started seven years ago.

It Begins: FXCM Doubles Yuan Margins, Warns Of Market "Disruption And Highly Illiquid Conditions"

The last time FX brokers, still hurting from the Swiss National Bank's revaluation shocker from last January which forced brand names such as FXCM to seek an urgent bailout, scramble to hike margins was in late June just ahead of the Greek "event risk" weekend, when  numerous brokers either hiked margins on EUR positions or went to "close only" mode due to "uncertainty surrounding the Greek debt negotiations... that could lead to high volatility on the market."
So, barely one week into the new year, one which has seen the stock market suffer its worst ever first week of trading, some FX brokers are not taking chances, and in the aftermath of the aggressive plunge in the Yuan (one we warned about a month ago), have decided to minimize client stop-out risk by hiking margins.
Case in point, here is FXCM with a just released warning about upcoming "highly illiquid conditions" leading to a doubling in Yuan margins:
Dear Client,

We believe there is a chance of disruption and highly illiquid conditions in the forex market during the coming weeks (and/or months). Please be aware that market gaps tend to occur over the weekend – that is, currencies trade at prices considerably distant from previous levels.

*IMPORTANT UPDATE*  

Margin requirements will double on the USD/CNH pair after market close on January 15, 2016. See a Complete List of New Margin Requirements

Please review your account to ensure that you have enough available margin to support any new positions. You may deposit additional funds at www.myfxcm.com or close positions as needed.
Follows the traditional disclaime which FXCM itself probably should have taken to heart one year ago when after the SNB's de-pegging the firm suffered tremendous losses:
Remember that forex trading can result in losses that could exceed your deposited funds and therefore may not be suitable for everyone, so please ensure that you fully understand the high level of risk involved.
The paradox here is that pre-emptive, if correct, warnings such as this one, tend to quickly become self-fulfilling prophecies as other brokers immediately follow suit and likewise increase margin requirements, which helps mitigate total loss potential but just as quickly soaks up liquidity from the market, leading to an even more fragmented market, prone to sudden, and quite dramatic moves.
The full list of FXCM margin increases is shown below; expect every other FX brokerage to promptly jump on the bandwagon.