Friday, July 15, 2016

Italy’s banking sector is looking increasingly vulnerable and analysts are starting to fear that the euro zone’s third largest economy could “go under,” warning of the potential for bank runs, credit rating downgrades and the threat to the wider European banking system.


We have reports from readers in Italy that ATM machines are being emptied. A run on banks is beginning in Italy.

https://www.armstrongeconomics.com/world-news/sovereign-debt-crisis/banking-panic-in-italy/
Bank runs, bailouts and downgrades? What Italy’s future could look like
Italy’s banking sector is looking increasingly vulnerable and analysts are starting to fear that the euro zone’s third largest economy could “go under,” warning of the potential for bank runs, credit rating downgrades and the threat to the wider European banking system.
“Italy could be a bigger threat to euro zone stability than Brexit,” Andrew Edwards, chief executive of London spread better ETX Capital said in a note on Tuesday. “The nation has a creaking banking sector that could undo all the European Central Bank‘s efforts to save the euro if not handled correctly.”
“Unlike other countries, Italy did not carry out a full spring clean of its banks post-Lehmans and there is trouble brewing with the country’s banks holding 360 billion euros ($400 billion) in non-performing loans (NPLs) – a third of all the euro zone’s bad debt and about a fifth of all consumer loans in Italy,” Edwards noted, highlighting the extent of Italy’s banking vulnerabilities.
http://www.cnbc.com/2016/07/06/bank-runs-bailouts-and-downgrades-what-italys-future-could-look-like.html

While Central Banks Have Gone All In, Delinquency Rates Rising. Is A New Banking Crisis imminent?

Technically Speaking: Breakout Or Market Meltup? – Lance Roberts
While Central Banks have gone all in, including the BOJ with additional QE measures of $100 billion, to bail out financial markets and banks following the “Brexit” referendum, it could backfire badly if the US dollar rises from foreign inflows. As shown below, a stronger dollar will provide another headwind to already weak earnings and oil prices in the months ahead which could put a damper on the expected year-end “hockey stick” recovery currently expected. 
https://realinvestmentadvice.com/technically-speaking-breakout-or-market-meltup/
Delinquency Rates Rising – Is A New Banking Crisis imminent?
The delinquency rate on loans is key in understanding banking. It answers one question: what percentage of loans is overdue for payment? The delinquency rate is by far the most useful indicator for “credit stress.” It seems, however, as if delinquency no longer counts. Few are paying attention to the quick and sudden rise of the delinquency rate. What does it tell us and is a new banking crisis imminent?
…
A clear danger sign: delinquency rates on commercial and industrial loans are creeping up. Source: St Louis Fed
In dollar terms the shift is even more pronounced. This is of course the result of our staggering debt levels, which are not apparent in the relative numbers. Source: St Louis Fed
In line with increasing loan delinquencies, charge-off rates on commercial and industrial loans are picking up as well (charge-off rates tend to lag somewhat). Source: St Louis Fed
Even if we are on the verge of a new banking crisis, the headline number will never tell us so.
https://mises.org/blog/delinquency-rates-rising-new-crisis-approaching
Former FDIC Chair Sheila Bair expects more pain ahead for US banks
“I think it’s been ill-advised to rely on monetary policy, but that still appears to be the only game in town.”

http://www.cnbc.com/2016/07/11/former-fdic-chair-sheila-bair-expects-more-pain-ahead-for-us-banks.html
Gerald Celente-Panic Of 2016 At The Doorstep


Published on Jul 10, 2016
At the beginning of this year, Gerald Celente, the publisher of the Trends Journal, put out a magazine cover that predicted the “Panic of 2016.” How close are we to the “panic”? Celente says, “We are at the doorstep, and it’s ready to go. Look at gold prices. Look at how they have been going up. They are up 28% year to date. I ask people, would you buy a bond where you know you are going to get less back than what you paid for it in 10 years? Or, do you think gold prices will be higher in 10 years than they are now? That’s why you are seeing gold as the safe haven.”
Join Greg Hunter as he goes One-on-One with Gerald Celente, publisher of The Trends Journal.
All links can be found here:  http://usawatchdog.com/separate-laws-…

Ireland exposes the flaws of using GDP as an economic measure

by Shaun Richards
Firstly let me welcome you all to what is already being called MayDay in the UK as it will see our second female Prime Minister. However as I noted yesterday there has been quite an event in the world of economic measurement that has occurred across the Irish Sea and it is something which has taken place in spite of all the “improvements” that were made with the ESA 10 changes. Indeed more than a few of you may be wondering if someone has been indulging rather too liberally in one of the boosts to GDP (Gross Domestic Product) that it brought namely the addition of illegal drugs such as cocaine.
The Financial Times summarised it thus.
That is the highest level of growth for decades and far outstrips the original estimate of Irish economic activity last year, which the official Central Statistics Office had put at 7.8 per cent. A growth rate of more than 26 per cent is nearly three times the highest level recorded during Ireland’s Celtic Tiger boom years in the early 2000s.
To be precise the annual rate of growth was revised upwards to 26.3% with the first quarter of 2015 being the main culprit as it recorded economic growth of 21%. It was only on the 22nd of last month that I pointed out that the Irish economy was doing well so here is the comparison with what we were previously told.
Preliminary estimates indicate that GDP in volume terms increased by 7.8 per cent for the year 2015.  GNP showed an increase of 5.7 per cent in 2015 over 2014.
As you can see 26.3% is the new 7.8%! This of course was quite a rate of economic growth in itself. Also we should not move on without considering the point that this is treble the rate of growth claimed in the Celtic Tiger boom which of course ended in a painful bust.
There is another consequence of all this and let me explain with something else from the 22nd of June.
In 2015 GDP was 203.5 billion Euros and GNP (Gross National Product) was 171.9 billion Euros.
I was using this to explain a problem I will return to in a moment. But you will get my point if I tell you that the new revised 2015 GDP is 243.9 billion Euros and the new 2015 GNP is 194 billion Euros. So they are 20% higher and 13% higher respectively! Let us just remind ourselves that this is for the year just gone and consider the scale of this when sometimes changes in GDP growth rates as small as 0.1% are debated and indeed forecast.
The gap between GDP and GNP
This has been a regular topic on here concerning Ireland.
The difference is that a lot of businesses in Ireland are non-domiciled there and send the money home. They want to take advantage of the low corporation tax rate and other benefits but do not consider it to be home. As you can see it is a big deal.
The difference is that the “big deal” as I called it has just got a lot bigger. The gap was previously reported as 31.6 billion Euros and is now 49.9 billion Euros. But this is only part of the story as GNP rose by 18.7% itself in 2015.
An Inflation Problem
We are regularly told that there is no inflation in the Euro area and consumer inflation in Ireland has been close to zero for some time. Thus you will not be surprised to note my eyes alighted on these inflation measures. The deflator for GDP rose by 4.9% in 2015 and the deflator for GNP rose by 4.5%. So if Ireland had its own monetary policy and used the widest inflation measure of all for monetary policy then it certainly would not have an official deposit rate of -0.4%!
Care is needed as consumer inflation is a significant part of the GDP deflator (24% in the UK for example) but is far from all of it. The catch is that as I look elsewhere I see few signs of the difference. For example we know that there is some services inflation around but if we look it falls well short of what we are told.
Services prices in Quarter 1 2016, as measured by the experimental SPPI, were on average 1.5% higher in the year when compared with the same period last year.
Actually services inflation was a fair bit higher early in 2014.
There was a burst of inflation in the output price index for manufacturing early in 2015 as the annual rate rose to 9.5% but by the end of the year this had faded. But we have a problem as you see output is recorded as much higher and it seems to have done so accompanied by higher prices! If only we could all do that…….
Ch-ch-changes
This came in the world of net trade so let me take you back to where we thought we were only a few short months ago.
Import growth during the year of 16.4 per cent outpaced that of exports at 13.8 per cent.
I pointed out back then that Ireland was doing its bit for world and European trade. However that story has expired also and been replaced by a new version.
On the expenditure side of the accounts exports grew by 34.4% between 2014 and 2015 (Table 6, at constant prices). Imports increased also, by 21.7%, over the same period.
So as you can see there was an exports surge and in fact rather than helping demand in other nations Ireland in fact has increased its own current account surplus. So export led growth for it but not so good for its trading partners as we observe yet another large change.
The revised current account surplus for 2015 was €26,157m, an increase of €22,954m on 2014.
The current account surplus is now on its way to 15% of GDP. So is it Ireland that has used a lower exchange rate to boost its exports in the same way as Germany? That point is a little tongue in cheek but there is a point to it.
Manufacturing
I did point out that there was a potential issue with prices being higher whilst output also surges. As the surge in prices was taking place then quarterly exports of merchandise trade rose from 30.1 billion Euros to 46.5 billion Euros. Apart from the obvious question of how this happened without the official statisticians noticing there is a lot which requires investigation here. The national accounts do provide a clue of sorts.
Industry (including building) advanced by 87.3% ( in 2015)
That happened without anybody noticing it for quite a while.
Comment
Let me now bring in some of the factors which have been at play here. A lot of aircraft leasing activity takes place in Ireland. This has been booked as an increase in assets and therefore GDP. An explanation has been provided by Colm McCarthy on the Irish Economy website.
There are roughly 750 commercial passenger aircraft on the Irish register for April 2016. The number actually based at Irish airports and serving Irish traffic is only about 100. Ryanair registers all its 340 aircraft here but only 10% are based at Irish airports.
There is debate over the numbers but not the principle. Also it appears that factors such as the patents of international firms have been booked in Ireland and counted in GDP. Did I say firms as this from the Central Statistics Office might mean one firm?!
As a consequence of the overall scale of these additions, elements of the results that would previously been published are now suppressed to protect the confidentiality of the contributing companies, in accordance with the Statistics Act 1993.
Even the Governor of the Central Bank of Ireland is concerned by this according to the Irish Times.
The Irish Times has learned Prof Lane met the CSO on Monday and made known his concerns that the GDP growth figures do not accurately reflect economic activity in Ireland.
Please do not misunderstand me I think that the Irish economy is growing as there are other measures such as the rise in employment. But the sad part is that we now have very little idea of at what rate! Rather ironically Ireland will be paying more to the European Union because of all of this and because of money it may never see. At least the rate of growth for net national income was a more subdued 6.5%. But it is time to hear from Marvin Gaye one more time.
Oh, what’s going on?
What’s going on?
Ya, what’s going on?
Ah, what’s going on?
Meanwhile I did point out on the 22nd of June that other measures pose questions as to the whole narrative.
Ireland and Luxemburg showing a very large difference between these two measures of household welfare. Using the AIC measure, Irish households are closer to Italian than Danish levels of welfare.
As the television series Soap used to tell us “Confused? You soon will be!”
Oh and as Claus Vistesen points out
Bonkers … it will likely lead to an upward revision of EZ GDP growth of 0.3pp in 2015. That’s 1.9% then, punchy

Cargo Volume At Chinese Ports Falls To 7-Year Low

More bad news for the world economy as China watches port volume fall to a 7 year low according to this WSJ report.
Cargo volumes through China’s ports grew at the slowest pace in seven years in the first half of 2016, according to an industry report that showed the country’s trade slump hitting its biggest gateways.
China port container volumes rose 2.5% in the January-June period from a year ago, research group Alphaliner said in a report this week, and the ports of Shanghai and Shenzhen—China’s two biggest sites for imports and exports—both saw container traffic decline 1%.
“Overall container volumes at Chinese ports are growing at the slowest pace since 2009,” Alphaliner said in its weekly newsletter on shipping industry trends. Chinese ports registered a 4.6% drop in volumes that year.
The sluggish business at China’s main gateways comes as the country’s trade downturn is accelerating. The China General Administration of Customs reported Wednesday that China’s exports, which have long been a central piece of the global economy, declined 4.8% in May while imports fell 8.4%.

Truck plows into crowd, killing at least 84 in Nice, France

Scene of chaos at Bastille Day celebration

Reuters
French police and forensic officers investigate the bullet-ridden truck that ran down scores of people Thursday night in Nice, France.


NICE, France — A truck driver barreled for more than a mile through Bastille Day revelers thronging the famed seaside promenade here Thursday, killing scores of people and sending a terror-scarred nation reeling again.
The driver slammed the massive vehicle, which an official said was loaded with explosives and weapons, into a crowd packed with families that had come to see the celebratory fireworks, leaving bodies in his wake.
At least 84 people were killed and 18 critically wounded, a French official said.
President François Hollande said in an early-morning televised address that the attack had “undeniable traits of terrorism.”


Truck driver kills dozens in Nice, France
A truck driver plowed through a crowd gathered on a coastal promenade at a Bastille Day celebration on Thursday in Nice, France, killing several dozens of people and sending hundreds fleeing from the scene. Photo: Getty Images
“France has been struck on its national day — July 14, a symbol of freedom — because human rights are denied by fanatics and France is of course their target,” Hollande said.
Witnesses said the driver steered the truck into the crowd deliberately, maintaining speed as he ripped through the revelers. The rampage ended in a hail of police bullets that killed the driver, bringing the truck to a halt, officials said.
“We thought he lost control. We all shouted: ‘Stop! Stop!’” said Nader Shafa’ai, an Egyptian tourist, who captured the mayhem on his video camera as the truck came careering through the crowd. “Then it was clear it wasn’t an accident.”
The footage Mr. Shafa’ai shot shows French police as they surrounded the white truck and fired rounds at the driver. The footage also shows scores of bodies under and behind the truck.
“I filmed it because I was in shock,” Shafa’ai said.
Reuters
French soldiers and police secure the area Thursday in Nice, France.
Christian Estrosi, the president of the region, said the truck driver fired shots in the crowd as he drove. Police searching the truck found it was loaded with arms and grenades, he said.
Images on French TV showed a cargo truck windshield pocked with bullet holes.

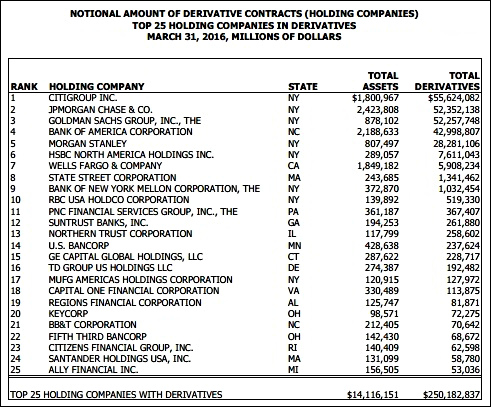
Citigroup Has More Derivatives than 4,701 U.S. Banks Combined; After Blowing Itself Up With Derivatives in 2008

Derivatives at Bank Holding Companies, March 31, 2016 (OCC Report)
By Pam Martens and Russ Martens: July 14, 2016
According to the Federal Deposit Insurance Corporation (FDIC), as of March 31, 2016, there were 6,122 FDIC insured financial institutions in the United States. Of those 6,122 commercial banks and savings associations, 4,701 did not hold any derivatives. To put that another way, 77 percent of all U.S. banks found zero reason to engage in high-risk derivative trading.
Citigroup, however, the bank that spectacularly blew itself up with toxic derivatives and subprime debt in 2008, became a 99-cent stock during the crisis, and received the largest taxpayer bailout in U.S. financial history despite being insolvent at the time, today holds more derivatives than 4,701 other banks combined which are backstopped by the taxpayer.
The total notional amount of derivatives sitting at Citigroup’s bank holding company is $55.6 trillion according to the March 31, 2016 report from the Office of the Comptroller of the Currency (OCC), one of the regulators of national banks. (See chart above.) Out of Citigroup’s total notional (face amount) exposure of $55.6 trillion in derivatives, $52 trillion of that is sitting at its insured depository institution, Citibank, which is still decidedly too-big-to-fail and would require a taxpayer bailout again in a collapse.
If you add in four other mega Wall Street banks (JPMorgan Chase, Goldman Sachs, Bank of America and Morgan Stanley) to Citigroup’s haul in derivatives, there is a staggering $231.4 trillion in derivatives or 93 percent of all derivatives in the entire FDIC banking universe of 6,122 banks and savings associations.
Didn’t the Obama administration tell the public that allowing these Frankenbanks to continue to gamble in derivatives while putting the U.S. economy and taxpayers at risk was going to end under his Dodd-Frank financial reform legislation passed in 2010? How could there have been meaningful reform of Wall Street if Citigroup and these other four banks are still holding a loaded gun to the taxpayers’ head?
Under the “Push-Out Rule” (Section 716 of the Dodd-Frank Wall Street Reform and Consumer Protection Act), insured banks were not going to be allowed to hold these derivatives when the rule was fully implemented in July 2015. The mega banks would have to “push-out” the derivatives to their uninsured affiliates so that the taxpayer wasn’t on the hook for future losses or bank implosions. But in December 2014, Citigroup was able to slip language into the must-pass spending bill that effectively repealed this critical Dodd-Frank provision and President Obama signed the bill into law.
According to OCC data, prior to Citigroup’s massive bailout in 2008, it held $41.3 trillion in notional derivatives as of March 31, 2008. Instead of regulators forcing the unruly bank to pare back its exposures, its tally today of $55.6 trillion shows it has been allowed to grow its derivative risks by 35 percent.
According to the General Accountability Office, this is how much Citigroup needed to remain afloat the last time it blew itself up: On October 28, 2008, Citigroup received $25 billion in Troubled Asset Relief Program (TARP) funds. Less than a month later, it was teetering again and received another $20 billion. But its capital moorings were so shaky that it simultaneously needed another $306 billion in government asset guarantees. And all of this disclosed money spigot came on top of the Federal Reserve secretly funneling to Citigroup over $2 trillion in cumulative loans over more than two years at interest rates frequently below 1 percent.
The official report on the financial crisis of 2008 from the Financial Crisis Inquiry Commission explained the interconnected nature of the derivatives crisis as follows:
“Large derivatives positions, and the resulting counterparty credit and operational risks, were concentrated in a very few firms. Among U.S. bank holding companies, the following institutions held enormous OTC derivatives positions as of June 30, 2008: $94.5 trillion in notional amount for JP Morgan, $37.7 trillion for Bank of America, $35.8 trillion for Citigroup, $4.1trillion for Wachovia, and $3.9 trillion for HSBC. Goldman Sachs and Morgan Stanley, which began to report their holdings only after they became bank holding companies in 2008, held $45.9 and $37 trillion, respectively, in notional amount of OTC derivatives in the first quarter of 2009. In 2008, the current and potential exposure to derivatives at the top five U.S. bank holding companies was on average three times greater than the capital they had on hand to meet regulatory requirements. The risk was even higher at the investment banks. Goldman Sachs, just after it changed its charter, had derivatives exposure more than 10 times capital. These concentrations of positions in the hands of the largest bank holding companies and investment banks posed risks for the financial system because of their interconnections with other financial institutions.”
The counterparties to this mass gluttony in derivatives by the mega Wall Street banks included the two government sponsored enterprises, Fannie Mae and Freddie Mac, and the large insurer, AIG.
In May of this year we reported that the U.S. government is still quietly paying out billions of dollars to Wall Street banks for derivatives held by Fannie Mae and Freddie Mac, companies the government was forced to place into conservatorship because of their massive losses during the 2008 crisis. In April of this year we reported the following about AIG’s derivative losses during the crisis:
“AIG received a taxpayer backstop of $185 billion and had to be taken over by the Federal government. But the bailout of AIG was in reality a backdoor bailout of the biggest Wall Street banks and their foreign big bank kin who had used AIG as a counterparty on their casino-like derivative bets and for securities loans that AIG could not make good on.
“It was eventually revealed that major Wall Street banks, foreign banks and hedge funds received more than half of AIG’s bailout money ($93.2 billion). Public pressure eventually forced AIG to release a chart of these payments, but the chart showed just a narrow window of disbursements from September to December 2008.  How vast the full total of payments were to the big banks is yet to see the light of day.”
The banking crisis and economic collapse in 2008 was the largest financial disaster in the United States since the Great Depression. To understand that the Obama administration and the U.S. Congress have not only failed to rein in the risks of a recurrence but have actually allowed the risks to dramatically grow, is an indictment of our entire political system and a siren call for the political revolution that Senator Bernie Sanders has now surrendered to the Clinton Wing of the Democratic Party — otherwise known as the Wall Street Banksters.
Related Article:
Interconnected Banks Pose Greatest Threat to U.S. Financial System

Dr. Lacy Hunt: Yes, The Economy Is Actually That Bad

by 
Debt. It’s good, it’s bad, there’s too much of it, the government keeps piling on more of it. What’s the deal?
You may have none, you may have too much, but one thing is certain, debt is a major driving force behind the world economy. Both in our personal lives and in the lives of immense corporations struggling to hold on in an ever-changing economy. Make no mistake, debt patterns will continue to shape all of our financial landscapes.
Given this unavoidable fact of life, when we had the chance to sit down with Dr. Lacy Hunt of Hoisington Investment Management to discuss his upcoming appearance at our Irrational Economic Summit in October, debt is where we began.
U.S. consumers have racked up almost $1 trillion in credit card debt, despite some saying this is a great sign, that this means consumers are optimistic and will buoy the economy, Dr. Hunt does not agree.
He immediately points out that debt is a two-edged sword and that if additional indebtedness doesn’t work to create income to pay down interest and principle, it is a no-win deal.
See, when you agree to spend borrowed money today, you’re leveraging that against your future income. That means that the dollars you’ll earn tomorrow are already spent and will not be there to use in the future for anything else. Seems obvious, right?
Of course, this is not a problem if you expect your income to increase as time marches along and your payments become due. But how many people in America are facing an increase in personal income when the standard of living hasn’t changed one iota in 20 years? Not many.
Unfortunately, this is not on the forefront of most people’s thoughts when they go to buy something like a new car. Dr. Hunt points out that new car sales are buoying portions of the economy, but that credit-lending standards have slipped, much like they did for mortgages prior to the housing crisis in 2008 (Harry has been talking about the auto sector soon getting turned on its head for months!).
1200px-Tesla_auto_bots
To illustrate this, Dr. Hunt points out that the average automobile loan has gone from six years to eight in order to allow less qualified buyers to purchase more expensive cars than they might otherwise have been able to afford.
This allows buyers to make smaller payments over a longer term, but also exposes them to the risk of missing any one of those 96 monthly payments.
But what about student debt? That has always been one way to invest in ourselves, and our children, and foster new revenue streams to pay down interest and principal. Dr. Hunt has bad news on that front, as well.
From Dr. Hunt’s interview with Rodney Johnson:
Unfortunately, the economy is performing so poorly that a lot of our college graduates are coming out and they’re having to settle for jobs that are not much better than what they would’ve received if they had gone directly into the labor force from high school.
Even classically “good debt” like a college education has become a non-performing investment. That’s scary because Dr. Hunt also points out that this deluge of debt, and our eagerness both as a country and as consumers to incur the “wrong type of debt” is killing growth.
This debt is slowing GDP growth and the growth of our personal incomes and investments. “That’s why”, Dr. Hunt points out, “the standard of living is unchanged from where it was 20 years ago.”
These are some cold, hard facts from one of the premier investment adviser’s in the country. It’s tough to read and painful to understand, but it’s true. And ideally, we’re in the business of truth and understanding the challenges facing all investors.
If you’re up for more of it, stay tuned because we’ll be bringing you excerpts from interviews with all our upcoming Irrational Economic Summit speakers in the weeks leading up the October event.
Thanks and play safe,

Robert Johnson Signature 
Robert Johnson
Editorial Director, Dent Research