Mac Slavo
June 3rd, 2013
SHTFplan.com
One year ago this month it was revealed that throughout the course of this crisis some40% of all wealth in America had been vaporized.
It was a stunning number to be sure, and one that many analysts
predicted would reverse as the Bernanke/Obama recovery took hold. Now, a
full year on, the news has not gotten any better. It’s gotten much,
much worse. According to a new report, the average American household has lost 55% of their net worth since the onset of the recession in 2008.
Many are likely holding to the belief that our benevolent government
politicians and financial leaders have taken the necessary steps to turn
this economy around.
But they’d be wrong.
The next wave of crisis is imminent and the end result will be a total wipe out for Americans:
“I think we are heading for a worse economic crisis than we had in 2007,”
[Peter] Schiff said. “You’re going to have a collapse in the dollar…a
huge spike in interest rates… and our whole economy, which is built on
the foundation of cheap money, is going to topple when you pull the rug
out from under it.”
…
According to Schiff, these numbers are unsustainable.
And the Fed has no credible “exit strategy.”
Eventually interest rates will rise… and when they do, Schiff
says, stocks will tank and bonds dip to nothing. Massive new tax hikes
will be imposed and programs and entitlements will be cut to the bone.
…
“The crisis is imminent,” Schiff said. “I don’t think
Obama is going to finish his second term without the bottom dropping
out. And stock market investors are oblivious to the problems.”
“We’re broke, Schiff added.
“We owe trillions. Look at our budget deficit; look at the debt
to GDP ratio, the unfunded liabilities. If we were in the Eurozone, they
would kick us out.”
Schiff points out that the market gains experienced recently,
with the Dow first topping 14,000 on its way to setting record highs,
are giving investors a false sense of security.
“It’s not that the stock market is gaining value… it’s that our
money is losing value. And so if you have a debased currency… a devalued
currency, the price of everything goes up. Stocks are no exception,” he
said.
“The Fed knows that the U.S. economy is not recovering,”
he noted. “It simply is being kept from collapse by artificially low
interest rates and quantitative easing. As that support goes, the
economy will implode.“
Via Money Morning
Peter Schiff knows
a thing or two about what’s going on, and he’s been sounding the alarm
since before 2008. He, like many others, understand that there is no way
out.
There is no credible financial or economic exit strategy.
The government knows this and that’s why they are actively implementing an expansive control grid across this entire country.
Those with insider knowledge fully understand what’s coming and they have been war-gaming large scale economic collapse and the widespread civil unrest that will follow.
Make no mistake. The powers that be have an exit strategy – it just doesn’t involve recovery, stability or your well-being.
Tuesday, June 4, 2013

Public Banking Conference good news: solutions already here for deficits, debt
Public Banking Institute’s 2013 conference explains, documents, and proves that economic solutions for deficits, debt, and full-employment are structurally:
- easy to understand and self-evident upon inspection
- easy to implement
- would improve our economy amazingly quickly and thoroughly
- State budget deficits end as state-owned banks create at-cost credit. The US has only one state with increasing budget surpluses: the only one with a state-owned bank.
- State taxes are entirely paid with ~5% public mortgages and credit.
- Trillions in taxpayer surpluses are returned from documented government CAFRs (Comprehensive Annual Financial Report) as at-cost credit replaces rainy-day funds.
- Truth in banking opens debt-free money: US national debt is ended forever, and we have full employment for the best infrastructure we can imagine (documentation here, here, here).
- Truth in banking and money can open truth everywhere: unlawful US wars can end, poverty can end, trillions of more dollars returned in the broader economy, and even truth from corporate media.
The conference link contains a complete schedule for access to each speaker’s contributions. The details on any one issue are many, and available at one’s interest to look.
What’s missing for the implementation of these solutions is that our 1% “leaders” will not and can not implement solutions without becoming visible in criminal culpability for having the current system that parasitically transfers literal trillions from the 99%.
Matt Taibbi: “If the public isn’t educated quickly, we won’t have a chance. The current system (of banking and finance) is completely corrupt.”
The solution to this problem is also obvious: prosecute obvious criminals in “leadership” in government, economics, and corporate media for fundamental fraud by lying to the 99% that debt is “money,” and lying in omission by failing to inform that public credit and money would solve all current economic issues. The public costs of this fraud are trillions of dollars, and needed-to-be-estimated harm to millions of Americans and significant totals of deaths. An alternative to criminal prosecution is Truth and Reconciliation.
Please remember: for 18 years I worked with both parties’ “leadership” to end poverty that had full academic agreement, full political agreement on paper, and two UN Summits. The 1990 World Summit for Children was the largest meeting of heads of state in world history, yet even the political organization at that level has been thwarted in policy realization. Poverty continues because the 1% use “leadership” in government and media to take no action and keep their inaction quiet from public attention.
Therefore, while I welcome anyone and everyone to learn whatever details of interest in public banking and monetary reform, I lived the intense learning and work to have appreciable command of the facts inclusive in the areas of ending poverty, I lived the work to help organized political agreement and meetings at the highest levels on the planet, and lived the life-changing defeat of all that work through political, economic, and media interest in competing areas. The 1% destroy democratic civic participation by removing choices from public consideration through their silence, despite obvious public enthusiasm when informed of the facts.
That said, the 100 million families who’ve received microcredit and worked their way out of poverty are surely appreciative of our work. These benefits saved ~100 million human lives, reduces population growth, and according to the CIA reduces the sole statistic most linked to global terrorism (infant mortality).
I see no policy realization in public banking without removal of our criminal 1% with competing interests in living off parasitic debt (full explanation here).
One of the ways to achieve that result is certainly through broad public education, providing choice to legislators of whether they wish to reclaim their hearts with public solutions, and local media and community outreach.
The solutions are here, with only parasites between humanity and their realization.
How The Federal Reserve is Suppressing a Recovery
 We like the look of the gold mining companies. They're relatively cheap. And sooner or later, they’re going to pop up too.
You know why? Ludwig von Mises explained more than half a century ago:
‘If it were really possible to substitute credit expansion (cheap money) for the accumulation of capital goods by saving, there would not be any poverty in the world.’Few people understand this. But the Federal Reserves ZIRP and QE policies are not bringing about a recovery. They're not bringing prosperity. They're bringing poverty. They're suppressing...repressing...depressing...a real recovery.
Why? Because a real recovery stifles the aforementioned ‘accumulation of capital good by saving.’ People need to save...and they need to invest in real productive enterprises. Those businesses, factories and enterprises then create real jobs and real wealth...goods...services... stuff.
See how simple this is? You save money. You use it to buy a sawmill or build a software company. You hire people. You cut logs. You produce boards and make a profit. The world is a more prosperous place.
But the Federal Reserve depresses interest rates. Savers get nothing for their efforts. Why bother to save when savings earn such trifling interest? People don’t save...
That's the purpose of Federal Reserve policy: to prevent people from saving. They want them to spend! To speculate! To party...party...party, until someone calls the cops.
No saving...no capital goods...no new production...no new jobs... Hey, no real recovery!
Mr. Keith Eubanks of Arlington, Massachusetts, explained the Fed's policy succinctly, in a letter to The Wall Street Journal:
‘Private investment drives economic growth. The policies currently labeled as "stimulus" and "austerity" are failing because both policies reduce private investment, contracting both the means and incentive for private citizens to invest in their futures.’In the US, the private sector is still about three-quarters of the economy. If the private sector is not saving and investing in the economy, it will not grow.
‘Stimulus’ policies increase deficits and allow the feds to spend more moneymore @ dailyreckoning
Asian shares creep up, nonfarm payrolls in focus
By Marc Jones
LONDON (Reuters) - The dollar and world shares
recovered from their lowest levels in a month on Tuesday and German Bund
futures eased, after weak U.S. data calmed concerns of an early cut in
central bank stimulus.The dollar was back above 100 yen and the U.S./ currency's index (.DXY) was clawing back some of the 1 percent falls seen on Monday after the Institute for Supply Management's (ISM) index of U.S. factory activity fell to 49.0, its lowest since June 2009.
European stocks (.FTEU3)<.stoxx50e> opened 0.6 percent higher, tracking an overnight rebound in U.S. and Asian shares and looking to snap a two-day losing streak that has left them at their lowest level since early May. (.EU)
"With (positive) closes in the U.S. and Japan we'll try to recover today," said Ouri Mimran, an equities strategist at Natixis in Paris. "A break above yesterday's high (on the Euro STOXX 50) will give the bullish signal."
As risk assets stabilized and investors kept positions tight ahead of the European Central Bank and Bank of England's monthly meetings on Thursday and key U.S. jobs data on Friday, German Bund futures dipped and peripheral euro zone debt edged up.
Commodity markets were also steadier. Copper climbed for a second session, while gold and oil were both little changed at $1,406 an ounce and $102 a barrel respectively.
(Reporting by Marc Jones; Editing by John Stonestreet)
Insight: Corbat faces ghost of Weill's deals in Citi's machines
By Dan Wilchins, David Henry and Nadia Damouni
(Reuters) - When Vikram Pandit was abruptly ousted as
Citigroup Inc's (C.N) chief executive late last year, senior bank
employees speculated for weeks about who would follow him out the door.Chief Operating Officer John Havens had already left with Pandit, and the employees bet the new CEO, Michael Corbat, would push out other Pandit loyalists. High on their list was Don Callahan, who headed operations and technology.
But when Corbat named his new team in January, he kept Callahan, albeit in a reduced role. People familiar with the matter said Callahan survived because he oversees an effort critical to both Corbat and bank regulators - simplifying and standardizing thousands of Citigroup's information technology systems. The process, which ramped up in the aftermath of the financial crisis, will take at least two more years to complete, they said.
Corbat's choice highlights how some 15 years after Sanford "Sandy" Weill merged Travelers Group and Citicorp to create Citigroup, the bank is still trying to integrate all its operations. For example, it still uses different account opening procedures and systems in different countries.
If Callahan gets it right, Citigroup will better track risks and satisfy U.S. regulators who have been pressing it to improve its systems for more than 10 years, and will more efficiently sell products to retail, corporate, and institutional customers. It will help bring down costs and raise revenue, potentially adding $750 million to annual profits starting in 2015 from improvements in consumer banking alone.
The bank spends around $18 billion a year - or about a third of its operating expenses - on operations and technology, including facilities, systems and hardware, making it a major area of concern for the board as well, two sources said. The board is considering hiring a new director with technology expertise to help monitor and assess management's efforts, they said.
Citigroup spokeswoman Shannon Bell said that the bank is simpler than it was before the financial crisis, having sold more than 60 businesses and $800 billion of assets that were not central to its strategy.
"We have worked diligently to integrate and modernize or replace legacy systems while investing in their safety and soundness," Bell said. "The continued integration and consolidation of our technology platforms will improve productivity and client service across the company, improving results for all stakeholders."
Weill, who retired as Citigroup CEO in 2003 and as chairman in 2006, told Reuters he was tireless in integrating companies he acquired.
Over about a dozen years, Weill built Citigroup into the largest U.S. bank, starting with a small consumer lending company in Baltimore and using it as a platform for a series of mergers and acquisitions with companies, including Primerica and Travelers.
"I don't want to sound cocky, but I think I managed it (Citigroup) very well," he said.
To Citigroup's critics however, its lingering technology problems are a sign of how the bank is too unwieldy for anyone to run.
"These institutions are too big and complex to manage effectively," said Gary Stern, former president of the Federal Reserve Bank of Minneapolis and co-author of "Too Big to Fail: The Hazards of Bank Bailouts," a 2004 book policymakers often cited during the financial crisis.
"It is a daunting challenge to effectively integrate systems," Stern added.
The technology issues have had a real impact on the bank's business, current and former executives said. As markets cratered during the financial crisis, for example, it took days for the bank to gather data about risks from different trading desks, according to a person involved in the quest to figure out the bank's exposure to particular securities, derivatives and counterparties.
"We were flying blind," said another former executive.
These problems also affected day-to-day operations of the bank. In 2005, for example, a customer service representative at a Citibank branch needed to know how to operate 89 different systems to sell every product the bank offered. At one point, the bank employed 30 people whose sole job was to help branch staff reset passwords to these systems, a former official at the bank said.
Corporate clients complained that they felt like they were being called on by hundreds of Citigroup sales people, each of whom was oblivious to the efforts of their colleagues, one of the former bank officials said.
‘TWO OF EVERYTHING'
The systems problems that Citigroup faces are, in varying degrees, issues for every major U.S. bank, most of which also arose through acquisitions. JPMorgan Chase & Co (JPM.N), for example, says it spends more than $8 billion a year on systems and technology, but generated some $6 billion of trading losses last year from the "London whale" scandal that were in part due to flawed valuation systems.
"A lot of these banks have grown through mergers, so they have a Noah's ark of platforms: they have two of everything and they have to all come together," said Ray August, a senior executive at CSC, which helps banks rationalize their systems.
Citigroup's problems may be worse than many of its rivals, say executives who have worked there and at other major banks.
Shortly after the turn of the century, the Federal Reserve Bank of New York demanded the bank integrate its credit risk management systems globally as well as its market risk management systems, a person familiar with the matter said.
A 2008 report by the New York Fed, that was made public through the Financial Crisis Inquiry Commission, found that almost a decade after the huge bank was cobbled together, Citigroup was still engaging in "significant integration efforts" in information technology, and characterized the bank's tech risks as "high."
The New York Fed declined to comment.
ONE BANK, TECHNICALLY
For Citigroup's management, technology is one of its biggest opportunities to cut costs and win new business, which is where Callahan comes in. He now oversees bank-wide operations and technology, and helps ensure that when businesses upgrade or build their systems, the result is compatible with what the bank already has.
He is also spearheading a five-year project, known as the "Global Data Roadmap," to create standards for different businesses to share information with one another. Citigroup is more than three years into that project.
Under a separate multi-year effort known as "Project Rainbow," the bank is moving its retail systems to a common platform that can be tweaked to fit local laws, but can still communicate with other parts of the retail business.
Corbat has said technology improvements will be responsible for much of the targeted efficiency gains in the consumer businesses. The improvements, a 2015 goal, could add as much as 25 cents per share, or some 6 percent, to the company's 2012 adjusted profits, according to Reuters estimates checked by two stock analysts. The efficiency goals for the whole company would bring Citigroup roughly in line with what other banks deliver.
Corbat said at a March investor conference that he is counting on Project Rainbow.
"Today, for example, we run different account opening procedures in almost every country," Corbat said. "We have to ensure that this process is identical for both our customers and our employees, whether it's happening in New York, Mexico City, or Warsaw."
(Reporting by Dan Wilchins, David Henry and Nadia Damouni in New York; Editing by Paritosh Bansal and Leslie Gevirtz)
The Fed and Inequality
Is the Federal Reserve a driving force
behind the post-recession growth in inequality? It’s a provocative idea,
voiced by writers including Neil Irwin and Robert Frank.
It is certainly true that inequality, in terms of both income and wealth, has widened since the recession. A study by the lauded economist Emmanuel Saez of the University of California, Berkeley, found that the top 1 percent of earners have accounted for all of the income gains in the first two full years of the recovery. Their incomes have climbed about 11.2 percent. The incomes of the 99 percent have declined by about 0.4 percent.
Those patterns repeat when looking at measures of wealth, meaning the value of a family’s assets, like its house and savings account, minus the value of its debts, like mortgages and credit card balances. A recent report from the Pew Research Center found that the wealth of the richest 7 percent of households climbed about 28 percent from 2009 to 2011. For the remaining 93 percent, average wealth dropped about 4 percent.
The Federal Reserve has been a major force propping up economic growth, even as Washington has started to slash the federal deficit and as droughts and debt crises abroad have taken their toll. A study by the Federal Reserve Bank of San Francisco estimated that the Fed’s aggressive policies have shaved 1.5 percentage points off the unemployment rate and have more broadly aided growth.
So if the Fed has been propping up the economy, has it also been propping up inequality? The argument would go something like this:
First, many financial experts consider the Fed’s policies a driving force behind the surge in the stock market. Since the depths of the crisis, the Dow Jones industrial average has more than doubled, increasing about 16 percent this year alone. Such gains have helped to lift the earnings and the net worth of the half of Americans who own stocks. But the wealthy have benefited disproportionately. According to recent research by the New York University economist Edward Wolff, the richest 10 percent of households own more than 81 percent of stocks, as measured by value.
A second factor is the rebound in the housing market, aided by the Federal Reserve’s purchase of about $40 billion in mortgage-backed securities every month. The effort has helped push down mortgage rates and make it cheaper for millions of families to buy a house or to free up some cash by refinancing. But because of tight credit standards, that windfall has mostly gone to the rich – families that meet the standards to refinance, and investors with enough cash to buy.
Looking at those two factors, there’s a strong argument that the Fed stands behind growth in inequality, particularly when it comes to wealth. But the picture is murkier when it comes to income. And experts sounded a note of caution about trying to work out the distributional effect that the central bank’s policies might be having more generally.
“I don’t think we know that much about it,” said Josh Bivens, an economist at the left-of-center Economic Policy Institute, a Washington-based research group. “It would be interesting to have a really determined academic look at the effect on all these asset groups and try to figure it out from there.”
Even if the Fed had stoked some wealth inequality through the stock and housing markets, he said, that would not be the full picture. How much did the Fed’s policies account for the housing turnaround, or the stock-price rebound? That would be hard to say. In the case of the stock markets, corporate earnings seemed the main factor, Mr. Bivens said.
Moreover, the fuller picture would need to take into account how the Federal Reserve might have eased earnings inequality by reducing unemployment. “High unemployment is much more destructive to wage growth for low-income workers than for high-income workers,” Mr. Bivens said. “The Fed might have done quite a bit to keep wages from falling even further at the low end.”
Other experts said they thought the Fed might have reduced inequality, if anything, and that one way or another it would be difficult to tell. “The effect is going to be at the margin if it is there at all,” said Joseph E. Gagnon, a former Fed official now at the Peterson Institute for International Economics in Washington. “It’s kind of a silly question to ask, though. It’s relevant to talk about international trade. It’s relevant to talk about technology. It’s relevant to talk about regulation. Monetary policy seems far down the list.”
One piece of analytical evidence that the Fed might be stoking inequality comes from the Bank of England. That central bank also undertook an aggressive round of asset purchases, and a report released last year found it helped the economy over all – but the rich much more than the poor.
Still, it described those distributional effects as unavoidable, and worth it in the long run. “Without the bank’s asset purchases, most people in the United Kingdom would have been worse off,” the report said. “Economic growth would have been lower. Unemployment would have been higher. More companies would have gone out of business. That would have had a detrimental impact on savers and pensioners along with every other group in our society.”
One way or another, it is a subject the Federal Reserve itself might have some interest in. Speaking at a conference in New York in April, Sarah Bloom Raskin, a Federal Reserve governor, posed the question of whether “inequality itself is undermining our country’s economic strength.” Her answer was an unequivocal yes. “I am persuaded that because of how hard these lower- and middle-income households were hit, the recession was worse and the recovery has been weaker,” she said.
“It is not part of the Federal Reserve’s mandate to address inequality directly,” she added, “but I want to explore these issues today because the answers may have implications for the Federal Reserve’s efforts to understand the recession and conduct policy in a way that contributes to a stronger pace of recovery.”
#Occupy Ankara #occupyturkey #occupytaksim #occupygezi #occupyistanbul #occupyankara #occupyizmir #direngezipark
*720-1080p modunda izleyin This video was taken in Ankara(capital of Turkey) on the first of June by Neo Beat Generation. 1 Haziran günü Kızılay Meydanı'nda ...
Source: occupygezipics

Water canon targets a single protester in Ankara (time/date unknown)
">
occupygezipics:
Water canon targets a single protester in Ankara
Protesters in Ankara shield themselves behind barricades.
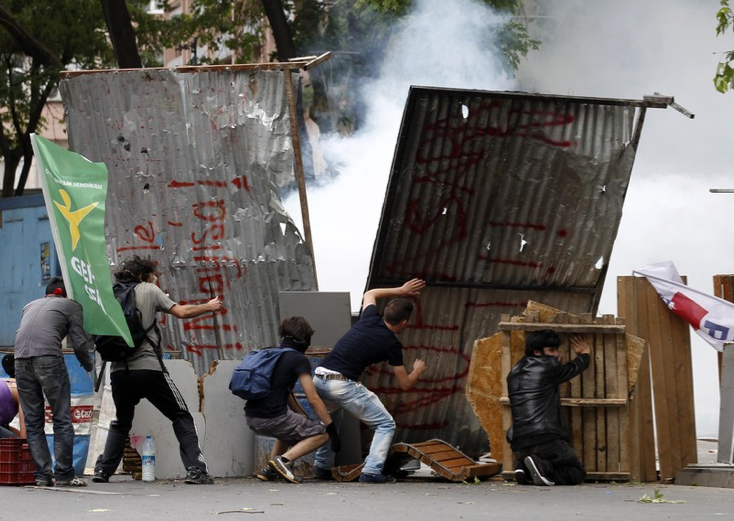
Protesters take cover behind makeshift shield in
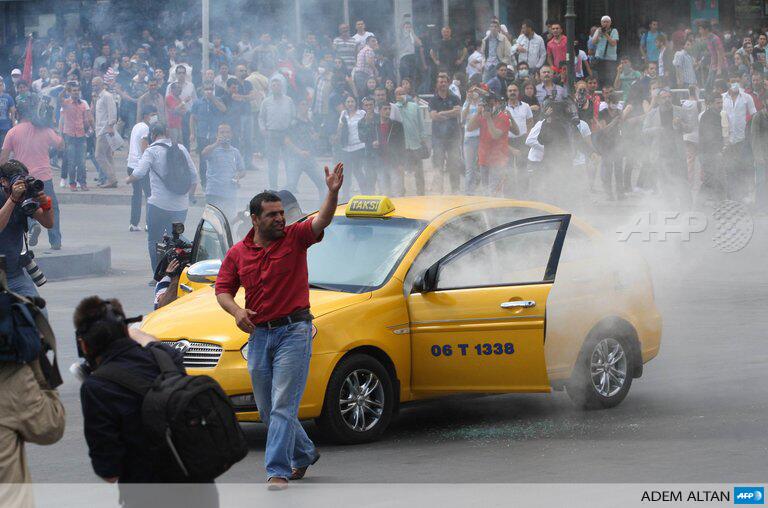
#occupyturkey #occupytaksim #occupygezi #occupyistanbul #occupyankara #occupyizmir #direngezipark
Subscribe to:
Posts (Atom)